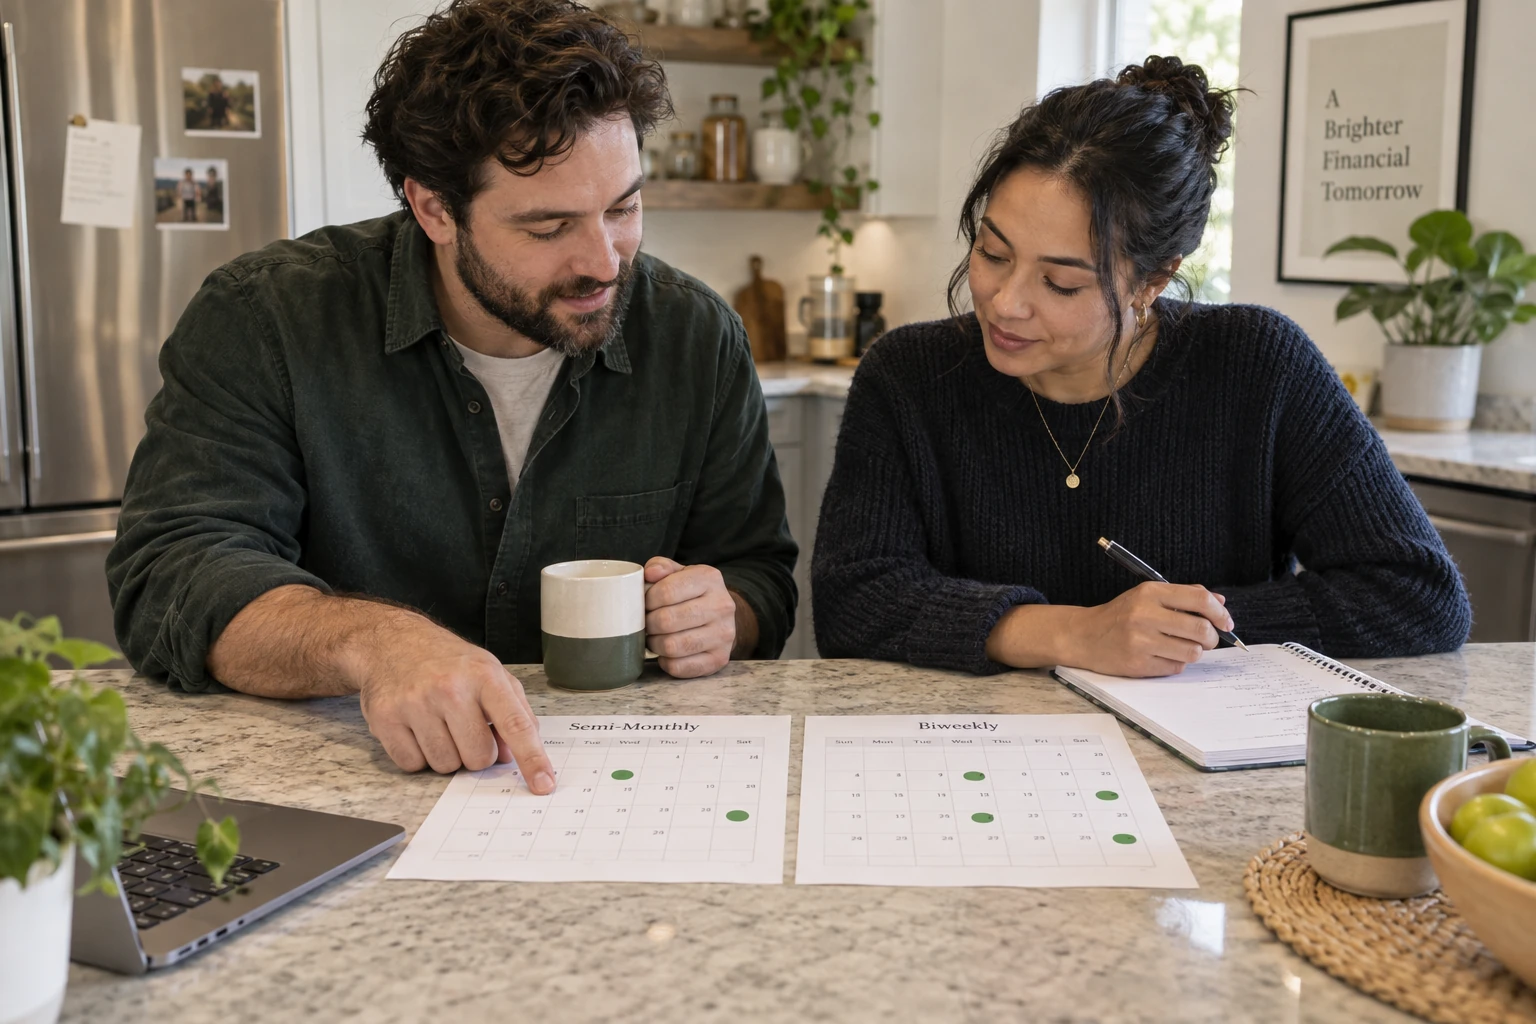
A template is a shape for your money, and the shape most of them have is a month. If you are paid every two weeks that is the wrong container, and no number of extra columns fixes it.
The template itself, free and with no email required
The printable biweekly budget template has all 26 blocks laid out exactly as described below. The rest of this article is why it is shaped that way, and how to build your own if you would rather.
What most templates get wrong
Search for a biweekly budget template and you mostly get a monthly spreadsheet with two income columns.
That is not a biweekly budget. It still assumes a month is the container, which is precisely the assumption that makes fortnightly pay hard. Two symptoms give it away: there is nowhere for a third paycheck to go, and bills are listed by name rather than by date, so nothing tells you which paycheck has to cover which bill.
The layout that works
One block per pay period, not per month. Each block is a small self-contained budget.
the payday date, and the date of the next payday. Everything in the block is what happens between those two dates.
The balance in the account you pay bills from, on the morning of the payday. This is the number every template omits and the one that makes the rest true.
What lands on this payday.
Listed by due date, not by category. This is the core of it. A bill belongs to the pay period it falls in, not to the month it belongs to conceptually.
Starting balance, plus income, minus bills, minus your buffer.
Extra debt payment, savings, spending. If it does not have a job, it does not survive the fortnight.
Building it in a spreadsheet
Due date · Bill · Amount · Paid ✓
26 blocks. That is a lot of copying, which is why step one is getting the dates right once.
Put your first payday in a cell, then =A1+14 down the column for 25 more rows. That column is the spine of the whole thing.
Counting forward in fourteens from one real payday gives you the same thing, and shows which two months carry a third paycheck.
With paydays in column A and a bill's due date in B, the pay period it belongs to is the last payday on or before it. Doing this by hand for 26 periods is where people give up.
Each block's closing balance becomes the next block's opening balance. Without it, an overspend in March vanishes rather than following you into April, which defeats the point.
If you would rather not build it, the printable version is the same layout with the 26 blocks already drawn, and a paycheck budget template does the same for any other pay cadence.
The three-paycheck months
Two blocks a year will have income and almost no bills, because your monthly bills are covered by the other two paychecks.
Do not let the template average this away. Leave those blocks looking as good as they are, and write in advance what the money is for. More on that here.
The columns most people add and should not
Tempting, and it undoes the whole design. The month is not the unit. If you want an annual view, total the 26 blocks at the end rather than rolling them into months.
50/30/20 is a monthly-income rule. Applied per pay period it produces different answers in three-paycheck months, and you will spend more time reconciling than budgeting.
A biweekly template's job is timing: what is due before the next payday. If you also want to track spending by category, that is a second sheet with a different purpose. Combining them is how a working template becomes an abandoned one.
When the spreadsheet stops being worth it
Spreadsheets are good at this and there is no reason to stop if it is working.
What they do not do is keep up. Balances change, a bill moves, payroll lands a day late for a holiday, a card gets paid off. Every one of those is a manual edit, and the template drifts from reality between the moments you sit down to fix it.
Cashrou is this template as an app: pay periods rather than months, bills in the period they land in, a running balance that follows you, and three-paycheck months that show up as what they are. You confirm your balances each payday and tick things off as they clear.
Seven days free, which is about one payday, and one payday is enough to know. If the spreadsheet is working, keep it.